



 2026-10-15
What Is an Emergency Fund and How Much Should You Save? Here's How to Calculate It Based on Your Financial Situation
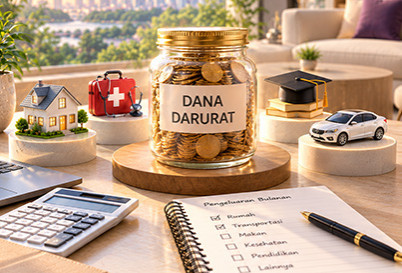
Life doesn't always go according to plan. Unexpected expenses can arise at any time, from sudden vehicle repairs and medical bills to losing a source of income. Without proper financial preparation, these situations can put significant pressure on your finances.
One way to prepare for unexpected financial challenges is by building an emergency fund. This financial reserve helps cover urgent expenses without immediately disrupting your monthly budget or other financial goals.
But how much should you have in an emergency fund? Does everyone need to save the same amount?
The ideal emergency fund varies depending on several factors, including monthly living expenses, financial dependents, and income stability. That's why it's important to understand what an emergency fund is, how much you should save, and how to calculate the right amount based on your financial situation.
What Is an Emergency Fund?
An emergency fund is money specifically set aside to cover unexpected expenses or financial emergencies. According to the Consumer Financial Protection Bureau (CFPB), an emergency fund is a cash reserve dedicated to unplanned expenses or financial emergencies, such as vehicle repairs, home maintenance, medical bills, or a loss of income.
Unlike savings for vacations, buying a car, or other planned expenses, an emergency fund is intended for situations that require immediate financial attention.
Some examples of situations where an emergency fund may be needed include:
- Losing your job or experiencing a sudden reduction in income
- Facing medical expenses that are not fully covered by insurance
- Repairing a vehicle that you rely on for work
- Paying for urgent home repairs
- Covering essential living expenses during a temporary loss of income
Having an emergency fund gives you a financial cushion to handle these situations without immediately dipping into savings allocated for other goals.
An emergency fund is an essential part of personal and household financial planning. In its Financial Literacy Series: Financial Planning, Indonesia's Financial Services Authority (OJK) emphasizes the importance of saving to build an emergency reserve that can be used for urgent and unexpected needs.
Here are several reasons why you should start building an emergency fund as early as possible.
- Helps You Handle Unexpected Expenses
Financial emergencies can happen at any time, even when your budget is already stretched. An emergency fund can help cover these unexpected costs without forcing you to completely rearrange your monthly spending plan.
-
Reduces Your Reliance on Borrowing
Without sufficient savings, you may need to borrow money or use funds intended for other purposes when unexpected expenses arise. The CFPB explains that limited savings during a financial emergency can lead people to rely on credit or loans, potentially creating additional financial obligations. With an adequate emergency fund, you can use money you've already set aside to manage urgent expenses.
-
Helps Cover Essential Living Expenses
If your income suddenly decreases or stops, essential expenses such as groceries, housing, transportation, and education still need to be covered. An emergency fund can provide temporary financial support to help you meet these needs until your financial situation improves.
-
Protects Your Long-Term Financial Goals
Without an emergency fund, you may have to withdraw money from your education savings, retirement fund, or other long-term savings when unexpected expenses arise. Keeping emergency savings separate from other financial goals can help you stay on track with your long-term plans.
The following table provides a general guideline based on different financial situations.
|
Financial Situation |
Recommended Emergency Fund |
|
Single with no dependents |
3–6 months of expenses |
|
Married with no children |
3–6 months of expenses |
|
Married with children or other dependents |
6–12 months of expenses |
|
Freelancer or someone with irregular income |
6–12 months of expenses |
Note: The six-to-twelve-month range is a more conservative financial planning consideration for individuals with dependents or greater income uncertainty. It is not a fixed requirement established by OJK.
For example, someone with a stable job and relatively predictable monthly expenses may consider starting with three to six months of essential expenses. Meanwhile, freelancers, business owners, or primary household earners may benefit from a larger emergency fund because of income fluctuations and greater financial responsibilities. The key is to set a realistic savings target based on your needs and financial capacity.
Calculating your emergency fund is relatively straightforward. You need to identify your essential monthly expenses and decide how many months you want your savings to cover.
The formula is:
Emergency Fund Target = Essential Monthly Expenses x Number of Months of Coverage
Essential expenses are costs you still need to pay even when your income is temporarily disrupted. These may include groceries, housing, transportation, education, healthcare, and other necessary financial obligations.
For example, suppose your monthly expenses are as follows:
|
Expense Category |
Monthly Amount |
|
Groceries and daily necessities |
Rp1,500,000 |
|
Housing and household expenses |
Rp1,200,000 |
|
Transportation |
Rp500,000 |
|
Healthcare and other essentials |
Rp300,000 |
|
Total |
Rp3,500,000 |
With essential monthly expenses of Rp3,500,000, your emergency fund targets would be:
- 3-month emergency fund: Rp3,500,000 x 3 = Rp10,500,000
- 6-month emergency fund: Rp3,500,000 x 6 = Rp21,000,000
- 12-month emergency fund: Rp3,500,000 x 12 = Rp42,000,000
These calculations provide a clearer picture of how much you may need to save based on your financial needs and the level of protection you want.
Beyond your monthly expenses, several other factors can influence your ideal emergency fund.
- Number of Financial Dependents
The more family members who depend on your income, the greater your monthly financial responsibilities may be.Education expenses, healthcare costs, and household necessities should all be considered when determining how much emergency savings you need.
- Income Stability
Someone with a stable monthly salary may face different financial risks than a freelancer or business owner whose income varies from month to month. For individuals with irregular earnings, maintaining a larger emergency fund may help cover essential expenses during periods of reduced income.
- Regular Financial Obligations
Mortgage payments, education expenses, and other recurring financial commitments should also be included in your calculations. Make sure your emergency fund accounts for all essential payments that must continue even when your income is disrupted.
- Health Conditions and Insurance Coverage
Your family's healthcare needs and existing insurance coverage can also affect how much emergency savings you should maintain. If you anticipate medical expenses that may not be fully covered by insurance, setting aside additional funds could be worth considering.
Once you've determined your savings target, the next step is creating a practical strategy to reach it.
- Start With a Realistic Savings GoalYou don't need to save a large amount all at once. If your final target feels overwhelming, start by saving enough to cover one month of essential expenses. Then gradually increase your savings until you reach your desired emergency fund. For example, if your essential monthly expenses are Rp3 million, you could make Rp3 million your first milestone before working toward Rp9 million or Rp18 million.
- Save Consistently Every MonthDetermine how much you can comfortably set aside each month based on your financial situation. For example, if you want to save Rp12 million over 24 months, you would need to put aside approximately Rp500,000 per month, assuming your target remains unchanged and excluding any additional returns. According to the Federal Deposit Insurance Corporation (FDIC), setting up automatic transfers to savings can help build an emergency fund and establish consistent saving habits.
- Keep Your Emergency Fund SeparateAvoid mixing your emergency savings with the money you use for everyday transactions. Keeping these funds separate makes it easier to track your savings progress and reduces the temptation to spend them on nonessential purchases.
- Use Additional Income to Boost Your SavingsBonuses, incentives, or other sources of additional income can help you reach your emergency fund target faster. Consider allocating a portion of this money to your emergency savings while balancing your other financial priorities.
- Review Your Savings Target RegularlyYour financial needs may change as you move through different stages of life. Getting married, having children, changing jobs, or facing higher living costs can all affect how much emergency savings you need. Review your emergency fund periodically to make sure it remains sufficient for your current financial situation.
Ideally, your emergency fund should be kept in a place where it is easily accessible, has relatively low exposure to changes in value, and remains separate from your everyday spending money. This is important because financial emergencies often happen without warning.
In its financial literacy materials, OJK also recommends considering savings products with minimal account fees so that your accumulated funds are not significantly reduced by ongoing charges. You may consider keeping your emergency fund in a savings account that allows convenient withdrawals, subject to the account's terms and conditions.
If you choose a fixed-term or goal-based savings product to build your emergency fund, make sure you understand the early withdrawal requirements, applicable fees, and any restrictions on accessing your money. It's generally advisable to keep at least a portion of your emergency savings in an account that allows quick access whenever urgent expenses arise.
An emergency fund should be used for situations that are genuinely urgent, unexpected, and could affect your essential needs or income. For example, you may need to use your emergency savings to repair a vehicle that is essential for work or to cover everyday living expenses during a temporary loss of income. On the other hand, expenses such as vacations, buying a new gadget, or shopping during promotional sales should generally come from a separate budget, as these are purchases that can be planned in advance.
After using your emergency fund, try to replenish it gradually so that you have sufficient savings available for future unexpected expenses.
An emergency fund is an important part of financial planning that helps you prepare for unexpected expenses and financial challenges. The ideal amount varies from person to person, depending on monthly expenses, financial responsibilities, and income stability.
By understanding your essential living expenses and setting a realistic savings target, you can gradually build an emergency fund that suits your financial situation.
To help develop a more structured savings habit, you can explore the Dana Impian feature in Muamalat DIN or Tabungan iB Hijrah Rencana from Bank Muamalat. These savings options can help you work toward specific financial goals based on your preferred savings target and contribution period, subject to the applicable product terms and conditions.
Before choosing a savings product, make sure you understand its withdrawal requirements and keep a portion of your emergency fund in an account that allows easy access when urgent needs arise.
Baca Juga :
- When Should You Start Saving for Retirement? Key Factors to Consider
- What Is Gold Buyback and How Does It Work?
- What Are Multazam, Hijr Ismail, and Maqam Ibrahim? Learn About Their Locations and Significance
- 3 Big Dreams You Can Start Preparing for Today
- Keep Dipping Into Your Savings? Try Building Assets One Step at a Time
- 5 Simple Ways to Manage Your Salary After Payday
- Decorating a New Home? Here’s Where to Start
- Planning to Perform Hajj? Here Are 5 Things You Can Start Preparing Today
- Planning for Different Goals? Gold Can Be Part of Your Financial Plan
- Planning to Perform Umrah Next Year? Here’s How to Start Saving Now
- Are Your Financial Goals Still on Track? It’s Time to Review and Reset
- Tap to Pay and Get Cashback with Bank Muamalat Shar-E Debit Card
- Looking for a Sharia Payroll Solution? Discover Bank Muamalat’s Tabungan iB Hijrah Payroll
- Cardless Cash Withdrawal at Bank Muamalat? Try Indomaret, Alfamart, or the Post Office
- Feeling Anxious? Here Are Islamic Ways to Calm Your Heart
- Can You Do Dhikr During Menstruation? Here’s What You Need to Know
- Renting vs. Buying a House: Pros, Cons, and Which Is Right for You?
- Still Keeping Your Money in a Savings Account? Discover Deposito Online iB Hijrah Muamalat
- From Emergency Funds to Qurbani: Plan Ahead with Tabungan iB Hijrah Rencana
- How Gold Can Help Protect Your Money Against Inflation
- Get a Samsung Galaxy Z Flip8 or Z Fold8 with Tabungan iB Hijrah Prima Berhadiah
- 5 Smart Money Habits That Make
- In This Economy, Should You Start Preparing for Hajj or Wait for the
- Beware of Social Engineering! Recognize the Scams Targeting Your Bank Account
- Know KPR iB Hijrah Baitullah: A Sharia Home Financing Solution with Hajj or Umrah Rewards
- Facing Hard Times? Here's the Complete Dua of Prophet Ayyub with Its Meaning
- Is Gold Still a Good Investment? A Smarter Way to Own Gold with Solusi Emas Hijrah
- Dhikr After Tahajjud: Recommended Remembrances to Complete Your Night Prayer
- How to Check Vehicle Tax Online and Pay It Easily
- Beware of Wrong Transfer Scams and Fake Transfer Receipts: Learn How to Protect Yourself
- Save Smarter with Bank Muamalat and Get a Samsung Galaxy S26 Series Smartphone
- Is the 50-30-20 Budget Rule Still Relevant? Here's How to Manage Your Salary in Today's High-Cost Economy
- Planning to Perform Umrah This Year? Here's How to Prepare Yourself for the Journey to the Holy Land
- Refer a Friend and Earn Rp50.000 with Bank Muamalat's Ajak Teman Hijrah Program
- 10 Recommended Acts of Worship in Muharram for Muslims
- Common Banking Scams You Should Know and How to Protect Yourself
- Looking to Buy a Home? Here's Why KPR iB Hijrah May Be the Right Choice
- Save for Hajj with Bank Muamalat's RINDU HAJI 2026 Program
- Looking for a Simple Sharia Investment? Discover Deposito Online iB Hijrah Muamalat
- The Meaning and Virtues of Takbir During Eid al-Adha
- Salary Day Scam Alert: How to Protect Yourself From Fake Bank Customer Service Fraud
- What Are Tarwiyah and Arafah Fasts? Benefits, Intentions, and How to Observe Them
- Beware of Fake QRIS Payment Scams: How to Stay Safe During Digital Transactions
- Intention and Step-by-Step Guide to Eid al-Adha Prayer
- Beware of Fake Customer Service Scams: How to Spot and Avoid Them
- Complete Hajj Packing List 1447 H for a More Focused and Comfortable Pilgrimage
- Safar Dua for Travel Safety: Arabic, Transliteration, and Meaning
- 34 Years of Bank Muamalat: Strengthening Synergy for a Meaningful Financial Hijrah
- Solusi Emas Hijrah Bank Muamalat: A Smarter Way to Own Gold with Sharia Financing
- Turn Your Savings Into Qurban Rewards with Tabungan Prima Berhadiah (TPB) Qurban Package 2026
- What Is Multiguna iB Hijrah? Benefits, Features, and How to Apply
- Rindu Haji 2026: A Journey to Baitullah with Greater Value in Every Step
- Muamalat DIN: A Practical and Complete Sharia Digital Banking Solution
- Kartu Haji Indonesia by Bank Muamalat: An Exclusive Debit Card for a More Comfortable Pilgrimage
- From Muharram to Dhulhijjah: Meaning and Virtues of the 12 Hijri Months
- Still Using Easy-to-Guess Passwords? It’s Time to Stay More Secure
- 5 Recommended Acts in Shawwal to Sustain Your Spiritual Momentum After Ramadan
- Powerful Duas for Finding a Job and Practices to Attract Sustained Provision
- Smart Ways to Manage Your THR and Post-Eid Expenses
- 5 Tips for a Comfortable and Peaceful Mudik Journey with Bank Muamalat
- What Is Zakat al-Fitr? Meaning, Intention (Niyyah), and How to Pay It
- 7 Acts of Worship Women Can Do During Menstruation in Ramadan
- What Is Lailatul Qadar? Meaning, Virtues, Recommended Deeds, and Tips to Seek the Blessed Night
- Make Business Transactions Easier with Muamalat Merchant App QRIS
- How Much Is Fidyah for Ramadan 2026? Amount per Day and How to Calculate It
- Rindu Haji 2026 Bank Muamalat: Reward-Based Hajj Savings Program for Better Pilgrimage Planning
- 8 Things That Invalidate the Ramadan Fast (and How to Make Your Worship More Meaningful)
- 5 Reasons Why Charity in Ramadan Brings Greater Rewards for Muslims
- 5 Productive Ngabuburit Ideas for Ramadan to Make Your Evenings More Meaningful
- The Meaning of Prophet Yunus’ Prayer and Its Virtues for Muslims Facing Hardship
- Save with Purpose Through the Tabungan Prima Berhadiah Humanitarian Aid Program for Palestine
- Home Renovation Before Ramadan and Eid Without Draining Your Savings
- When Gold Prices Rise, Choose a More Thoughtful Way to Own Gold
- How to Invest Your Salary in Sharia Mutual Funds via Muamalat DIN
- 7 Things to Do Before Ramadan to Be More Spiritually Prepared
- APK File Scam on the Rise: Risks, Red Flags, and How to Protect Yourself
- Protect Your Personal Data to Secure Your Banking Transactions
- Beware of Quishing: QR Code Phishing Scams You Need to Watch Out For
- Recognizing Impersonation Scams: Protect Your Data and Financial Transactions
- Beware of Fake Promotions and Prizes: Common Scams During the Holiday Season
- Sleeping According to the Sunnah: Turning Rest into an Act of Worship
- When Sustenance Feels Tight, Reflect on These 5 Quranic Verses About Charity
- Must-Know Guide: Indonesia’s 2026 National Holidays and Long Weekend Opportunities
- A Practical Guide to Exchanging Money at Money Changers
- Udzur Syar’i: Definition, Types, and Real-Life Examples in Daily Worship
- A Practical Guide to Shalat Jamak for Travelers and Those in Difficulty
- How to Unblock Muamalat DIN? A Complete and Safe Guide
- A Complete Guide to Qobliyah and Ba’diyah Prayers: Timing, Intentions, and Total Rakaat
- Ramadan Is Three Months Away: Smart Ways to Prepare Your Ramadan Budget Early
- Why Predawn Charity Is Special? Recommended Prayers and How to Practice It
- Quba Mosque: The Mosque Where a Single Prayer Holds the Reward of an Umrah
- Top Up TapCash, Flazz, and e-Money Made Easy with Muamalat DIN
- 7 Daily Good Deeds with Great Rewards
- What Is Miqat? Understanding Its Meaning, Types, and Locations for Hajj and Umrah Pilgrims
- 2026 Hajj Cost Officially Reduced: Pilgrims to Pay Around Rp54 Million
- How to Use QRIS Abroad Easily and List of Supported Countries
- Find the Right Shar-E Debit Card for Your Needs
- Feeling Anxious and Restless? Here Are Powerful Prayers to Calm Your Heart and Mind
- 5 Budgeting Methods to Keep Your Finances Organized and Under Control
- Smart Ways to Maximize Profit Sharing with the CASATD Bundling 2025 Program
- Gold Prices Are Rising? Here’s the Sharia-Based Gold Financing Solution You Should Know
- Live a More Blessed Life: Invite Your Friends to Hijrah with a Sharia Account
- Turn Your Longing into a Journey with the Rindu Haji Program
- Looking for a Safe Investment? Here Are the Advantages of Gold Financing at Islamic Banks
- Small Charity, Big Blessings: Simple Ways to Earn Rewards Every Day
- 5 Most Recommended Sunnah Fasts: Dalil, Intentions, and Their Virtues
- The Difference Between Debit and Credit Cards You Need to Know
- Plan Your 2026 Qurban with Ease Through Muamalat DIN’s Dana Impian
- Giving While Investing? Understand CWLS and How to Place Your Funds
- The Proper Way to Perform Wudu: Pillars, Sunnah, and Things That Invalidate It
- What Is Waqf? Definition, Rulings, Types, and Virtues
- The Virtue and Recitation of Ayat 1000 Dinar for Seeking Sustenance and Ease
- 5 Effective Ways to Plan Your Retirement Fund Comfortably
- National Customer Day 2025: Bank Muamalat Brings the Spirit of Think Customer to Life
- 5 Effective Tips to Keep Your Bank Account Safe
- Mindful Living: Simple Living, Lighter Finances
- How to Easily Pay Your Vehicle Tax Online with Muamalat DIN
- Powerful and Accepted Duas (Doa Mustajab): Complete with Arabic, Transliteration, and Meaning
- Complete Guide to Getting a Passport in 2025 (With Updated Fees)
- From Dreams to Action: How to Start Saving for Your Life Goals Today
- Freedom to Choose Your Home, with Affordable and Sharia-Compliant Financing
- Longing for Hajj but Short on Funds? Start Saving Here!
- Inactive Bank Account? Here’s What It Means, the Risks, and How to Reactivate It
- 5 Powerful Prayers of Prophet Musa for Peace of Mind, Guidance, and Sustenance
- Affordable Sharia Mortgage for Young Couples
- One-Time Deposit, Lifetime Benefits
- Start from Just Rp100,000, Here's How to Save for Hajj the Sharia Way
- Suitable for Young Couples! Here's How to Prepare for a Sharia-Compliant Wedding Fund
- How to Start Saving for Hajj or Umrah from Zero
- Smart Saving Strategies to Prepare for Rising Education Costs
- Secure and Sharia-Compliant Investment with Muamalat’s iB Hijrah Online Deposit
- Make the Most of This School Holiday with Bank Muamalat
- Your Path to a More Blessed Financial Life Starts with a Financial Hijrah
- 5 Virtues of Muharram and Recommended Sunnah Practices According to the Prophet Muhammad (SAW)
- Welcome the Islamic New Year 1447 H with These Meaningful Prayers Before and After Maghrib
- Need a Prayer Answered? Here's How to Perform Salat al-Hajah (The Prayer of Need)
- Understanding 9 Types of Islamic Contracts in Sharia Banking
- An Easy & Sharia-Compliant Way to Invest in Gold Safely
- Why Insurance Matters? A Wise, Shariah-Compliant Way to Secure Your Future
- Complete Guide to Eid al-Adha Prayer: Intention, Steps, and Sunah Practices
- A Complete Guide to the Recommended and Mandatory Acts of Hajj
- The Virtues of Dzulhijjah: 5 Highly Recommended Acts of Worship During This Sacred Month
- The Complete Guide to Tahajjud Prayer: Meaning, Steps, and Benefits
- Stay Safe from Phishing Links: Here's How to Protect Yourself
- How to Perform Salat al-Tawbah: A Complete Guide to the Repentance Prayer
- What Is Qurban? A Complete Guide to Its Meaning and Practice in Islam
- 3 Essential Tips to Stay Healthy During Hajj
- 12 Sacred Places to Make Du’a in Makkah
- What Is Hajj? Types, Requirements, and Its Virtues
- Achieve Financial Well-Being by Switching to a Sharia Bank Account
- The Fasting of Prophet Dawood (AS): Intention, How to Do It, and Its Benefits
- The 10 Key Rituals of Hajj: A Complete Step-by-Step Guide
- Living Frugally, Enjoying Life: It All Starts with Smart Financial Management
- Why Wait? Start Your Hajj Journey While You're Young—Here’s Why It Matters
- 5 Smart Strategies to Grow Your Money for Maximum Gains
- Should You Perform Umrah or Hajj First? Here's What to Consider Before Deciding
- Embrace the Blessings of Syawal with Ajak Teman Hijrah
- The Reward of a Year’s Fasting: 5 Virtues of Fasting in Syawal
- 7 Fun Activities to Enjoy When You’re Not Traveling for Eid
- How Much THR is Appropriate for Your Family? Here's How to Calculate It!
- Complete Guide to Zakat Fitrah: From Intentions to Proper Procedures
- Chasing the Blessings of Lailatul Qadar with These Acts of Worship
- 7 Profitable Business Ideas During Ramadan You Should Try
- 4 Quran Verses on Fasting During Ramadan
- 5 Recommended Acts of Worship During Menstruation in Ramadan
- 5 Virtues of Charity During Ramadan
- How to Perform Tarawih Prayer Alone at Home
- 6 Tips to Stay Fit and Healthy During Ramadan
- 5 Productive and Blessed Worship Goals for Ramadan
- The Power of Dhuha Prayer: Intentions, Rituals, and Benefits
- Complete Guide to Filing Your Annual Income Tax Return in Indonesia
- How to Register for Hajj Plus and the Requirements You Need to Prepare
- The Virtues of the Month of Sha’ban and Recommended Practices
- How to Manage Your Finances Before Ramadan for a More Peaceful Fast
- Intention and Guidelines for Making Up Missed Ramadan Fasts: What Every Muslim Should Know
- Safe and Easy Gold Investment? Choose Sharia-Compliant Gold Installments
- What is Isra Miraj? Understanding Its Meaning, History, and Lessons
- Take Note! Essentials for Your New Home
- 5 Smart Tips for Owning Your Dream Home Within Budget
- Finding Peace and Blessings in Every Drop of Rain
- 2025 Hajj Costs and Regular Hajj Registration Process Explained
- 5 Virtues of the Month of Rajab and Recommended Acts of Worship
- Smart Financial Management Despite 12% VAT Cancellation
- 9 Essential Preparations for Your First Umrah
- Steps to a Healthier, Happier, and More Meaningful Life in 2025
- 5 Prayers for Seeking Halal and Blessed Sustenance
- Save More, Stress Less: Minimalism for Young Adults
- What Are Hajj Embarkation and Debarkation? Understand These Crucial Steps in Your Hajj Journey
- Spread Kindness and Earn Blessings through ZISWAF
- When’s the Best Time to Prepare Your Child for Hajj? The Answer is Now!
- Make Your Dream Home a Reality Before 30 with Sharia Financing
- Is Your Financial Health on Track? Let’s Evaluate and Prepare a 2025 Strategy!
- Start Early, Retire Happily with Pensiun Hijrah
- Impulsive Buying: What It Is and How to Stop It for Better Financial Health
- Sharia Deposits Explained: The Halal Way to Invest and Grow Your Wealth
- Why You Should Start Monday and Thursday Fasting
- What is the 50-30-20 Method? Benefits & How to Apply It
- Secured Your Hajj Slot? Don’t Forget to Plan for the Final Payment!
- Tips to Know Before Choosing a Banking Product
- What is a Mutual Fund? Exploring Investment the “Fruit Salad” Way
- 4 Tips to Prepare Your Child’s Education Fund Early
- Recharge Your Mind Without Draining Your Wallet
- Empowering the Young Generation to Embrace Change with Bank Muamalat
- 5 Tips to Start Saving for Hajj While You're Young
- Why Gold Installment is the Right Choice for Investment
- Muamalat DIN: Simple, Fast, and Secure Digital Islamic Banking
- Beware of the Dangers of Online Gambling: Financial, Health, and Legal Risks
- Become #HajiAnakHebat: Prepare Your Child for Hajj Early!
- 6 Safe Ways to Achieve Your Dream Home
- Apa Itu Phising? Pengertian, Ciri-ciri, dan Cara Menghindarinya
- Waspada Penipuan dengan Aplikasi yang Bisa Mengendalikan Perangkat dari Jauh
- Berangkat Haji Tahun Ini? Ini Hal-hal yang Harus Anda Perhatikan
- Umrah Selagi Muda, Kenapa Engga?
- Tips Menghindari Modus Sniffing
- 5 Cara Berhemat & Kelola Keuangan dengan Tepat
- Layanan Syariah di Era Modern: Optimalkan Kelola Keuangan Secara Islami
- 5 Tips to Maximizing the Lifespan of Your THR
- 5 Steps to Catch the Blessings of Laylatul Qadr
- The Merits of Performing Umrah in Ramadan
- 5 Tips to Stay Fit and Healthy During Ramadan
- Cashless Society in Indonesia
- 4 Way to Strengthening Relationship in Ramadan
- Avoid Overspending during Ramadan: Here's How
- Do This to Multiply Your Blessings During Ramadan
- Perbedaan Bank Syariah dan Bank Konvensional
- 4 MANFAAT MENABUNG DI BANK SYARIAH
- EVALUASI KONDISI KEUANGANMU SETELAH LEBARAN
- 5 HAL YANG DAPAT KAMU LAKUKAN AGAR PEMBAYARAN ZAKAT FITRAH TETAP AMAN & HIGIENIS
- PENGELOLAAN DANA AGAR IDUL FITRI LEBIH BERKAH & TETAP HEMAT
- JAGA SILATURAHMI DI BULAN RAMADAN MESKI TETAP DI RUMAH
- TIPS LEBARAN TETAP BERLIMPAH, BERKAH TANPA MUDIK
- TIPS SEHAT MEMPERSIAPKAN PUASA RAMADAN DI TENGAH PANDEMI
- TIPS MENABUNG MUDAH DAN LANCAR
- TIPS & AMALAN MENJELANG RAMADAN
- KIAT AGAR HIDUP LEBIH BAHAGIA
- TINGKATKAN IBADAH SAAT DI RUMAH
- TIPS BELANJA AMAN DAN HIGIENIS DI SWALAYAN
- 4 TIPS MENGONTROL PENGELUARAN BULANAN
- 6 HAL YANG HARUS KAMU BIASAKAN DALAM MENGELOLA UANG
- TRANSAKSI NON TUNAI DENGAN MUAMALAT QRIS MEMPERMUDAH KEBUTUHANMU
- TIPS AGAR TETAP FOKUS KETIKA BEKERJA DI RUMAH
- TIPS MENABUNG UNTUK MEMBELI RUMAH BAGI MILENIALS
- 5 LANGKAH SEDERHANA MEMULAI HIDUP SEHAT
- 5 CARA MENINGKATKAN KEPERCAYAAN DIRI
- 5 TIPS MENGATUR KEUANGAN DALAM ISLAM
- 6 TIPS BERDAGANG ALA RASULULLAH
- TETAP SEHAT & PRODUKTIF DI MUSIM HUJAN SAAT PANDEMI
- TIPS MENGATUR AKTIVITASMU AGAR TETAP EFEKTIF
- TIPS HEMAT AKHIR BULAN
- KIAT TRANSAKSI AMAN DI ATM MUAMALAT
- TIPS MENABUNG EFEKTIF MENJELANG AKHIR TAHUN
- AMALAN SAAT HUJAN
- ALASAN KAMU HARUS BANGET MENABUNG
- JAGA KESEHATANMU MENJELANG MUSIM PANCAROBA DI TENGAH PANDEMI
- MANFAATKAN SKILL-MU SEBAGAI TAMBAHAN PEMASUKANMU
- TIPS KEUANGAN MENGHADAPI RESESI
- 3 CARA MENGHEMAT UANGMU SAAT PSBB DIPERKETAT
- TIPS MENJAGA KESEHATAN MENTAL SELAMA PANDEMI
- TIPS OLAHRAGA UNTUK PEMULA
- Gaya Hidup Hemat Untuk Masa Depan
- Tips Belanja Hemat Saat New Normal
- Tips Mengelola THR Saat Pandemic Virus Corona
- Tips Hemat Selama Puasa
- Jenis-Jenis Riba
- Pengertian Maysir, Gharar, dan Riba
- 4 Tips Mudah Menabung Kurban
- 3 Hal yang Dilarang dalam Bisnis Syariah
- Konsep Bisnis Syariah
- Hindari Rekening Berstatus Dormant
- Mengetahui Tentang Kuadran Prioritas
- Manfaat Memiliki Tabungan Rencana di Bank Muamalat
- Beberapa Ide Bisnis saat Pandemi
- Tips Mengisi Liburan di Rumah saat Pandemi
- Tips Efektif Menabung
- Tips Memakai Masker Agar Tetap Aman
- Tips Menyimpan Daging Kurban
- Puasa Sunah Sebelum Iduladha
- Tips Mempersiapkan Dana Kurban
- Tips Menabung di Era New Normal
- Tips Sehat Berpuasa saat Corona
- Persiapan Fisik Menjelang Ramadhan
- Tips dan Waktu yang tepat untuk berjemur di pagi hari saat karantina di rumah
- Tips Berolahraga saat New Normal
- Tips Sehat Menghadapi New Normal
- Tips Alokasi Pengeluaran yang Bisa Dihemat Selama #DirumahAja
- Tips Beradaptasi dengan New Normal
- 8 Golongan Penerima Zakat Fitrah
- Tips Menjaga Silaturahmi Ramadan saat Pandemic Covid 19
- Tips Ibadah Selama Karantina di rumah
- Tetap Produktif & Sehat dengan Work From Home (Kerja dari Rumah)
- Wakaf Al-Qur’an Bagi Para Penghafal Alquran
- Sedekah Kurma untuk Sekolah Dhuafa di Aceh
- Ayo Bantu Masyarakat Lebak Membangun Jembatan yang Layak
- Muamalat DIN: New Mobile Banking Application from Muamalat Bank
- Bank Muamalat Activities on November 10 – 16, 2019
- Bank Muamalat Activities on November 1st and 8th, 2019
- Bank Muamalat Activities on October 28 and 30, 2019
- Gopay & Ovo Can Now be Topped Up at Bank Muamalat’ ATM and Muamalat DIN
- Bank Muamalat Activities on October 23 and 25, 2019
- Bank Muamalat Activities on October 14-20, 2019
- Tips to Effectively Save Your Money in a Bank
- Bank Muamalat and Baitulmaal Muamalat Build Houses through “Program Rumah Berkah Muamalat”
- Bank Muamalat Cleans The Shiratal Mustaqim Mosque in Makassar
- Hajj Savings: One of the Best Gifts for Our Parents
- Hajj Savings: One of the Best Gifts for Our Parents
- Bank Muamalat Distributes Funds and Collaborates with New Partner
- Get a Collection of Stylish Muslim Fashion Here!
- Bank Muamalat Activities from 17th to 21st September, 2019
- Bank Muamalat Received 2 Awards as The Best Sharia Product and The Best Active Sharia Card
- Bank Muamalat Presents Bereavement Compensation to Marbot Family in Lampung
- Bank Muamalat Participates in 2019 National Customer Day
- Blessing House Aid in Lebak Regency Banten as a Form of Distribution of Zakat Bank Muamalat and Baitulmaal Muamalat (BMM)
- Bank Muamalat Indonesia activities 23-24 August 2019
- Mau nabung sambil dapat hadiah yang bisa dipilih online? Begini caranya!
- Bank Muamalat Meluncurkan Tabungan iB Hijrah Rencana Kurban dalam Acara “Qurban Terbaikku”
- Sudah siap berkurban? Yuk simak tata caranya!
- Bank Muamalat Campaigning #AyoHijrah Movement Moves with Bloggers
- Apa Sih Prinsip Bisnis Syariah Itu?
- Step to avoid the risk of theft of your ATM data
- 4 steps going home without burden
- Let’s Manage Your Width Personal Benefits!
- Save Tips During Fasting Time
- Tourism to Bangka Belitung: Unique Customs and Nature Ciamik Waiting
- I wanna be a fire fighter Sir said Fajar.
- Bank Muamalat holds a fun walk for the 27th anniversary
- Let's invest in 011 Sukuk Retail!
- Pay PLN bills? Use Mobile Banking and Internet Banking!
- Bank Muamalat contributed to the trauma healing of Tsumani Pandeglang disaster victims
- Internet Banking for Browser-based Transaction Needs
- How to avoid fraud under the guise of a bank
- Check out the following online security tips if you do frequent shopping online!
- The new Bank Muamalat Debit Card with NSICCS technology
- Are you preparing for future needs? then you need to open a savings plan now
- Let's check the Calculation of Profit Sharing in Savings
- Your Mobile Banking is blocked? Let's look at the reset steps.
- How to Manage Your Financial Needs in Ramadhan
- Check your financial needs from Bank Muamalat web!
- Saving Lifestyle for Future Plan
- Effective Tips on Saving
- Savings Plan Muamalat as a financial planning solution at the beginning of the year
- Allocate Your Year End Bonus as A Future Investment Fund
- The Difference of Interest and Profit Sharing
- Differences in KPR Syariah and Conventional
- Take the mortgage at Bank Muamalat to Realize Your Dream Home
- Prepare your senior fund towards The Golden Age
- These Financial Tips Will Save You at The End Of The Month
- Capital Financing for Your Businesses
- These Tips Will Make You Succeed in Applying for Financing to Sharia Bank
- Want an Additional Income? Join Gerai Muamalat
- IB Giro Muamalat Saving for Your Business Needs
- Plan for Qurban Saving? Use IB Muamalat Saving Plan
- Plan Your Umrah and Hajj Saving While You’re Still Young
- Take Advantange of Various Discount Promo as a Step Savings in Shopping
- Tips to Secure Your Transaction
- Eid Al-Fitr Time Shopping? Use Mualamat’s Shar-E Gold Card
- E-banking Muamalat; Easier Way For Zakat Payment
- Just Received Your Holiday Pay? Instead of Splurging, Why Not Deposit?
- New School Year Preparation Made Easy and Lenient with TabunganKu from Bank Muamalat Indonesia.
- Shar-e Card from Bank Muamalat Indonesia for Ease of Transaction when Traveling Abroad
- How to Register and Activate Your Muamalat Mobile Banking Service
- 5% Mortgage for your Family Planning Solution
- How to Activate the Hajj and Umrah Savings in Bank Muamalat Indonesia
- Monthly Bill Payment Becoming More Practical with Mobile Banking Bank Muamalat Indonesia
- Things to Look for in Financial Planning in the New Year
- 5 General Terms which must be known in Islamic Banking Trade - Part 2
- 5 General Terms which must be known in Islamic Banking Trade Part 1